Best Loan Calculator Online in Nigeria
Finding the right loan can be difficult when you only look at the interest rate or monthly payment. A loan calculator makes the process easier by showing how much you may need to repay, how much interest you could pay, and how the repayment period can affect the total cost of borrowing.
The best loan calculator online in Nigeria is one that lets you enter the loan amount, interest rate, repayment period, and other relevant charges. A useful calculator should also help you understand the difference between your monthly payment and the total amount you will repay.
Loan calculators can be useful for personal loans, salary loans, business loans, car loans, mortgages, and other forms of credit available in Nigeria. However, a calculator provides an estimate based on the information entered. The actual amount you pay depends on the terms offered by your lender.
What Is a Loan Calculator?
A loan calculator is an online financial tool that estimates the cost of borrowing money.
You normally enter details such as the amount you want to borrow, the interest rate, and the repayment period. The calculator then estimates your regular repayment and the total amount you may pay during the loan period.
For example, if you want to borrow ₦500,000, the calculator can help you estimate how much you may repay each month over 12, 24, or 36 months.
The result can help you compare different loan options before making a borrowing decision.
A good loan calculator may also show the total interest, remaining balance, and repayment schedule. Some advanced calculators allow you to include processing fees, insurance costs, or other charges.
Why Use a Loan Calculator in Nigeria?
Borrowers often focus on the amount they will receive. However, the amount you receive is only one part of the cost of a loan.
The interest rate, repayment period, fees, and method used to calculate interest can all affect the final amount you pay.
A loan calculator helps you see these numbers before you accept a loan.
It can help you:
- Estimate your monthly repayment
- Calculate the total interest
- Calculate the total repayment
- Compare different repayment periods
- Compare different interest rates
- Understand how loan fees affect the cost
- Plan your monthly budget
- Check whether a loan fits your expected cash flow
- Compare loan offers from different lenders
- Understand the effect of borrowing a larger or smaller amount
This makes a loan calculator useful even before you apply for a loan.
What Makes the Best Loan Calculator Online in Nigeria?
There are many loan calculators available online, but they do not all provide the same information.
The best loan calculator for Nigerian borrowers should be simple to use and should provide enough information to make a useful comparison.
Loan Amount
The calculator should allow you to enter the exact amount you want to borrow.
For example, you may want to calculate a loan of ₦200,000, ₦500,000, ₦1,000,000, or a larger amount.
The loan amount is important because interest is normally calculated based on the amount borrowed or the outstanding balance, depending on the lender and the interest method.
Interest Rate
The calculator should allow you to enter the interest rate provided by the lender.
Pay attention to how the lender presents the rate. Some lenders may quote a yearly rate, while others may quote a monthly rate.
Do not assume that two rates are directly comparable until you know the period and calculation method used.
Repayment Period
A useful loan calculator should allow you to change the repayment period.
You may be able to calculate a loan over several months or years.
A longer repayment period can reduce the amount you pay in each instalment. However, it can also increase the total interest paid over the life of the loan.
This is why it is important to look at both the regular payment and the total repayment.
Interest Method
The method used to calculate interest can make a significant difference.
Two common methods are reducing balance and flat rate.
With a reducing balance method, interest is calculated based on the amount still owed. As the outstanding balance falls, the interest charged can also fall.
With a flat rate method, interest is calculated using the original loan amount for the agreed period. The interest is then included in the repayment calculation.
A calculator that lets you understand or select the correct interest method can give you a more useful estimate.
Fees and Other Charges
Interest is not always the only cost associated with a loan.
Depending on the loan, you may encounter processing fees, management charges, insurance costs, or other charges.
A calculator that allows you to enter additional charges can provide a better estimate of the overall cost.
You should still check the lender’s official loan offer because the calculator can only use the figures you provide.
How Does a Loan Calculator Work?
A basic loan calculator uses the information you enter to estimate your repayment.
The main inputs are usually:
Loan amount
Interest rate
Repayment period
Repayment frequency
Interest calculation method
Some calculators also include fees and other charges.
For a standard repayment loan, the calculator uses the interest rate and repayment period to determine the amount required for each instalment.
It then adds the instalments together to estimate the total repayment.
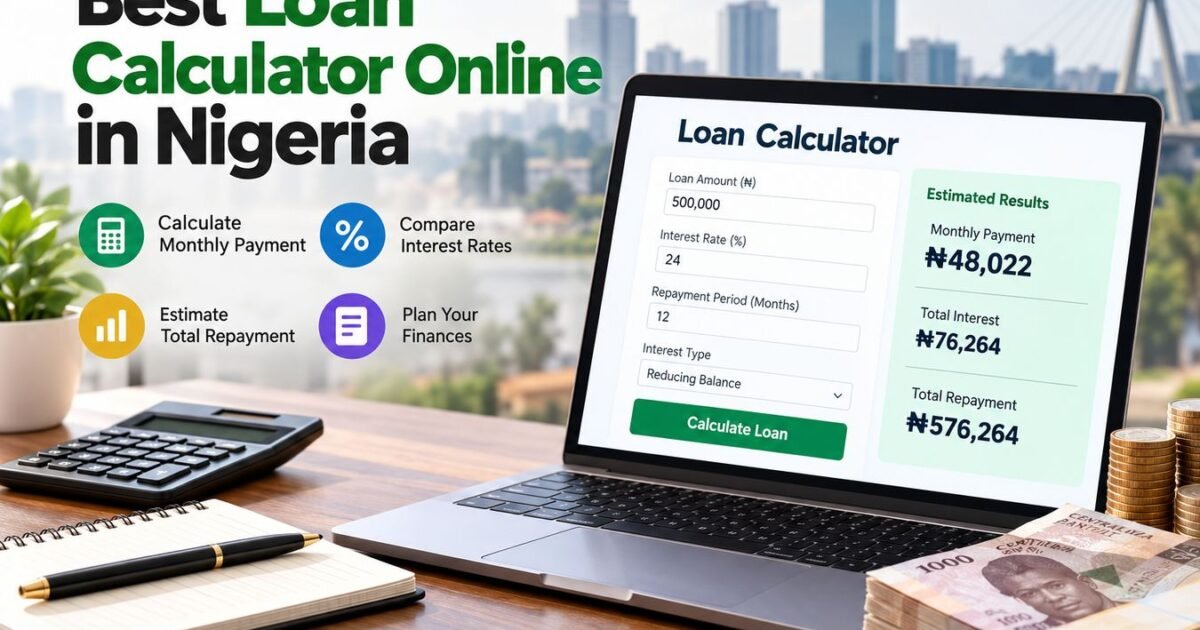
For example, suppose you borrow ₦500,000 and the calculator estimates a monthly payment of ₦48,000 for 12 months.
The estimated total repayment would be about ₦576,000.
The difference between the amount borrowed and the total repayment represents the estimated cost of interest, before considering any additional fees.
The actual result will depend on the interest rate, calculation method, fees, and exact terms of the loan.
Reducing Balance vs Flat Rate
Understanding the difference between reducing balance and flat rate interest is one of the most important parts of using a loan calculator.
Reducing Balance
Under a reducing balance method, interest is calculated using the amount that remains unpaid.
As you make repayments, the outstanding principal generally becomes smaller.
This means the interest component can also become smaller over time.
For many standard instalment loans, the monthly repayment may remain the same while the portion going toward interest and principal changes throughout the repayment period.
Flat Rate
With a flat rate calculation, interest is based on the original loan amount rather than the amount that remains outstanding.
This can make a flat rate appear simple because the interest calculation starts with the original principal.
However, a flat rate and a reducing balance rate with the same percentage are not necessarily equal in cost.
For this reason, you should not compare loan offers by looking only at the advertised percentage.
Use the total repayment to understand what the loan will actually cost.
How to Calculate Loan Repayment
There are several ways to calculate loan repayment.
The easiest method for most people is to use an online loan repayment calculator.
You enter the amount you want to borrow, the interest rate, and the repayment period. The calculator then estimates your payment.
For a simple flat interest calculation, you can first calculate the interest using the loan amount, interest rate, and period.
For example, suppose a lender offers a ₦100,000 loan with a flat annual interest rate of 20 percent for one year.
The estimated interest would be ₦20,000.
The estimated total repayment would therefore be ₦120,000 before any additional charges.
If the lender charges a processing fee, insurance cost, or another charge, the actual cost can be higher.
A reducing balance loan uses a different calculation because interest is based on the outstanding balance.
This is one reason an online calculator can be more convenient than calculating everything manually.
Example of a Nigerian Loan Calculation
Consider a borrower who wants to take a ₦500,000 loan.
The lender offers an annual interest rate of 24 percent and a repayment period of 12 months.
If the loan uses a standard reducing balance calculation, the monthly payment will be calculated using the outstanding balance and the agreed interest rate.
The borrower can then compare the estimated monthly payment with their income and regular expenses.
Now imagine the same loan is extended to 24 months.
The monthly payment may become lower because the repayment is spread over a longer period.
However, the borrower may pay more interest in total because the loan remains outstanding for a longer time.
This example shows why the best loan calculator should allow you to change the repayment period and compare the results.
The most affordable monthly payment is not always the lowest total cost.
How to Use a Loan Calculator Online in Nigeria
Using a loan calculator is usually straightforward.
Step 1: Enter the Loan Amount
Enter the amount you plan to borrow.
Use the actual amount in Nigerian naira rather than the amount you think you can repay.
Step 2: Enter the Interest Rate
Enter the interest rate stated by the lender.
Check whether the rate is annual or monthly.
If you are unsure, ask the lender to explain how the rate is calculated before entering it into the calculator.
Step 3: Enter the Loan Period
Enter the repayment period.
This could be several weeks, months, or years depending on the loan.
Make sure the calculator uses the same period stated by the lender.
Step 4: Select the Interest Method
If the calculator provides this option, select the method used by the lender.
Do not guess.
Ask the lender whether the quoted rate uses a reducing balance method, flat rate method, or another calculation method.
Step 5: Add Fees
If the calculator supports additional charges, enter the processing fee and other known costs.
This can make the estimate more realistic.
Step 6: Review the Results
Look at more than the monthly repayment.
Check the estimated total repayment and total interest.
If fees are included, check the total cost after fees.
Step 7: Compare Different Options
Change the repayment period or interest rate and see how the result changes.
This can help you understand the cost of different loan offers.
Why You Should Compare Total Repayment
A common mistake is to choose a loan because the monthly repayment looks affordable.
For example, one loan may require ₦50,000 each month while another requires ₦60,000.
The first loan may appear cheaper.
However, if the first loan lasts much longer, you could pay more money in total.
Always compare the total amount you will repay.
The total repayment tells you how much money will leave your pocket over the entire loan period.
You should also compare the amount you actually receive with the total amount you must repay.
This is especially important when fees are deducted before the loan reaches your account.
Loan Calculator for Salary Loans
Salary earners in Nigeria often use loan calculators to estimate how a loan may affect their monthly income.
A calculator can help you see the expected repayment before applying.
For example, if your regular income is ₦300,000 per month, you should consider how a monthly loan repayment would affect your other expenses.
Your rent, food, transport, school fees, utilities, savings, and existing debt may all compete for the same income.
A calculator cannot decide whether a loan is affordable for you, but it can show the size of the expected repayment.
Loan Calculator for Personal Loans
A personal loan calculator can be useful when planning expenses such as education, household needs, emergencies, or other personal costs.
Before taking a personal loan, calculate the total amount you are expected to repay.
Do not focus only on the amount deposited into your account.
Check whether the lender deducts any charges before disbursement.
If you borrow ₦500,000 but receive less because of an upfront charge, you should consider both the amount received and the amount you are required to repay.
Loan Calculator for Business Loans
Business owners can also use a loan calculator to estimate the cost of borrowing for working capital, equipment, inventory, or expansion.
For a business loan, the repayment should be considered alongside expected business cash flow.
A monthly repayment may be manageable during a strong sales period but difficult during a slower period.
A calculator can help you test different loan amounts and repayment periods before making a decision.
Loan Calculator for Car Loans
Car financing can involve a larger loan amount and a longer repayment period.
A calculator can help you estimate the monthly cost and total interest.
When calculating a car loan, remember that the cost of the loan is not the same as the full cost of owning the vehicle.
You may also have expenses for fuel, maintenance, insurance, registration, and repairs.
The loan calculator only deals with the financing part unless those additional costs are specifically included.
Loan Calculator for Mortgages
Mortgage calculations can involve larger amounts and longer repayment periods.
A mortgage calculator can estimate regular payments and total interest based on the information entered.
However, property financing may involve additional costs such as legal fees, valuation costs, insurance, taxes, and other charges.
Always review the complete mortgage offer rather than relying only on the calculator result.
Common Mistakes When Using a Loan Calculator
A calculator is only as useful as the information entered into it.
One common mistake is entering the wrong interest rate.
Another is confusing a monthly rate with an annual rate.
Some borrowers also forget to include fees.
Another mistake is choosing the longest repayment period simply because it produces the lowest monthly payment.
The lower payment may come with a higher total cost.
You should also avoid assuming that the calculator result is the exact amount the lender will charge.
Lenders may use different calculation methods, rounding rules, payment dates, fees, and other terms.
What a Loan Calculator Cannot Tell You
A loan calculator can estimate repayment costs, but it cannot tell you whether a lender will approve your application.
It also cannot determine your creditworthiness.
A calculator does not automatically know your income, existing debts, credit history, employment status, or other factors that a lender may consider.
It also cannot replace the loan agreement.
The lender’s final offer should contain the terms that apply to your loan.
If the calculator and the lender’s official repayment schedule produce different figures, ask the lender to explain the difference before accepting the loan.
How to Choose the Best Loan Calculator Online in Nigeria
When choosing a calculator, look for one that is easy to understand and supports Nigerian naira.
It should allow you to enter the loan amount, interest rate, and repayment period.
A better calculator should also help you understand total interest and total repayment.
If possible, choose a calculator that allows you to account for fees and different interest methods.
A repayment schedule can also be useful because it shows how the loan balance changes over time.
Most importantly, the calculator should clearly state that its results are estimates.
Tips for Comparing Nigerian Loan Offers
Start by collecting the full details of each loan offer.
Write down the loan amount, interest rate, repayment period, repayment frequency, processing fees, insurance charges, and other costs.
Then enter the figures into a loan calculator.
Compare the monthly repayment.
Next, compare the total repayment.
Then compare the total cost after adding all known fees.
Also check whether the interest rate is fixed or can change during the loan period.
Finally, read the loan agreement carefully before accepting the offer.
A loan with a slightly higher monthly repayment may still be cheaper overall if it has a shorter term or lower total interest.
Is an Online Loan Calculator Accurate?
An online loan calculator can be mathematically accurate when the correct information is entered and the calculator uses the same calculation method as the lender.
However, the result may not match the final lender figure.
This can happen because of fees, payment dates, rounding, interest calculation methods, insurance, or other charges.
For this reason, treat the result as an estimate.
The lender’s official repayment schedule should be used to confirm the final amount.
Should You Use a Loan Calculator Before Applying?
Yes.
Using a loan calculator before applying can help you understand the potential cost of borrowing.
It can also help you decide how much you actually need to borrow.
Instead of applying for the largest amount available, you can calculate different loan amounts and see how each one affects the repayment.
This gives you more information before making a financial commitment.
Final Thoughts
The best loan calculator online in Nigeria is one that gives you more than a simple monthly payment.
It should help you understand the loan amount, interest rate, repayment period, total interest, total repayment, and relevant fees.
The most important numbers to compare are the amount you receive, the amount you repay each period, and the total amount you will repay over the entire loan.
Always check how the lender calculates interest. A quoted percentage can mean different things depending on whether the lender uses a reducing balance method or a flat rate method.
Use a loan calculator as a planning tool, not as a replacement for the lender’s official loan terms.
Before accepting any loan, review the complete offer and make sure you understand the total cost, repayment schedule, fees, and conditions.
Frequently Asked Questions
1. What is the best loan calculator online in Nigeria?
The best loan calculator is one that allows you to enter the loan amount, interest rate, repayment period, and relevant fees. It should show the estimated regular payment, total interest, and total repayment.
2. Can I use a loan calculator for Nigerian naira loans?
Yes. A loan calculator can be used for loans denominated in Nigerian naira. Enter the exact figures provided by the lender and make sure the interest rate and repayment period use the same units as the lender’s offer.
3. Does a loan calculator show the exact amount I will repay?
Not always. A calculator provides an estimate based on the information entered. The actual amount may differ because of fees, insurance, interest calculation methods, payment dates, rounding, or other lender terms.
4. What is the difference between flat rate and reducing balance interest?
A reducing balance method calculates interest based on the amount that remains unpaid. A flat rate method calculates interest using the original loan amount for the agreed period. The same percentage rate can therefore produce different total costs.
5. Does a longer loan period reduce the cost of a loan?
Usually, a longer repayment period reduces the amount required for each payment, but it can increase the total interest paid. Use a loan calculator to compare both the regular payment and the total repayment.
6. Should I use a loan calculator before taking a loan?
Yes. A loan calculator can help you estimate the repayment and compare different loan amounts, rates, and repayment periods. You should still review the lender’s complete loan agreement before accepting the loan.